What awaits prediction markets as the Democrats take control of Congress?
Written by ChandlerZ, Foresight News
On November 16, a joint letter led by Democratic Senator Adam Schiff and addressed to the U.S. Commodity Futures Trading Commission (CFTC) drew far more attention than a routine political statement across Washington’s financial and gambling regulatory circles.
On the surface, Senators including Adam Schiff called on the CFTC to withdraw or suspend the enforcement of the fair access regulatory interpretation the agency published on November 5. But buried in the fine print of the letter, the lawmakers also demanded the CFTC preserve all correspondence related to the policy, and provide written confirmation of this requirement.
In Washington’s political playbook, demanding that executive agencies preserve correspondence is almost always a precursor to Congress exercising its subpoena power and launching formal investigative hearings.
The letter was deliberately released in mid-November due to a delicate power gap created after the November 3 midterm elections. While Democrats won majority control of both the House and Senate in the midterms, the 20th Amendment to the U.S. Constitution mandates that the 120th Congress will not be sworn in until January 3, 2027. It is only at that point that the new majority bloc will formally assume seats and leadership control of all congressional committees, while the White House remains under the stewardship of the incumbent president.
During the nearly two-month window before the formal power handover, a two-way race is unfolding in Washington. On one side, the CFTC, not yet subject to the checks and balances of a Congress under new control, is releasing a flood of rule interpretations and case-specific directives at a rapid clip. On the other, Democrats poised to take over committee chairmanships across both chambers are locking down executive agency records in advance, laying the groundwork for the oversight and accountability work they will launch next January.
Who Gets to Decide Where Sports Contracts Can Be Traded?
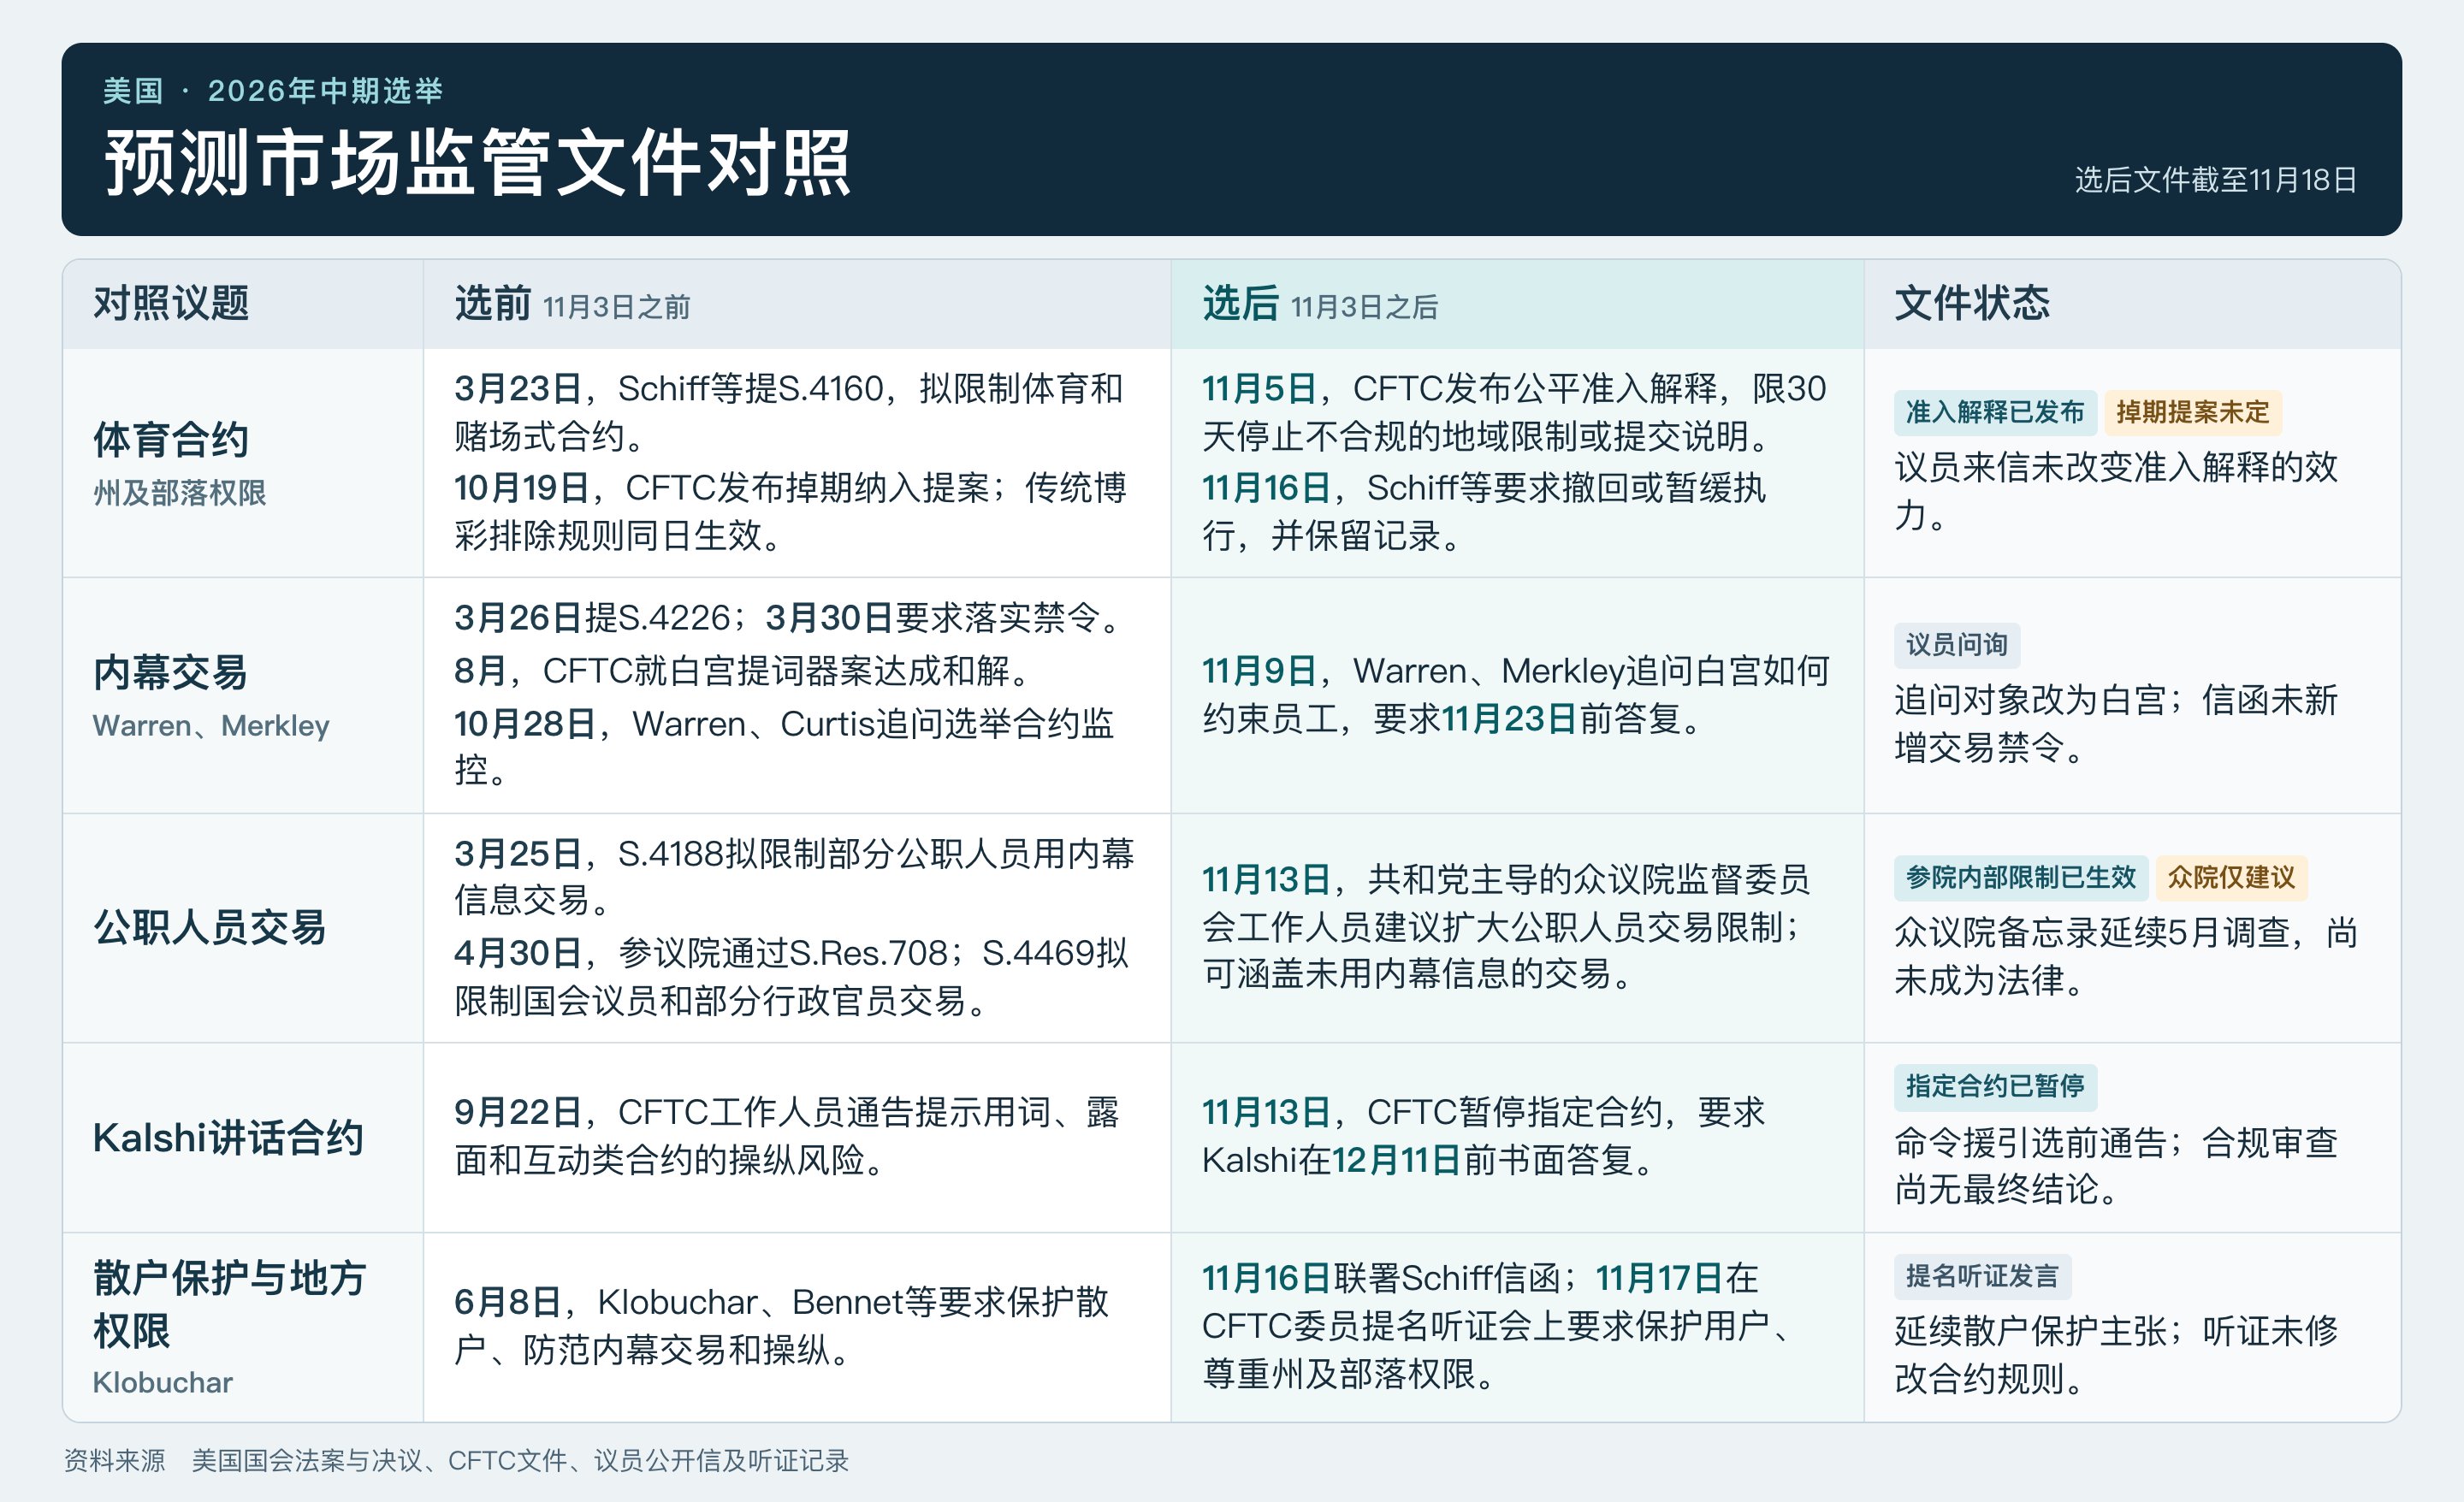
On March 23 this year, Schiff joined Republican Senator John Curtis and Democratic Senator Catherine Cortez Masto to introduce Bill S.4160, which seeks to ban federally registered platforms from listing contracts tied to sports events and casino-style games.
By November 16, Schiff and Cortez Masto had co-signed another document, again calling on the CFTC to withdraw or pause enforcement of the fair access interpretation. The March bill targeted what products platforms are allowed to list; the November letter addresses a separate question: whether already listed contracts can be made accessible to users subject to local restrictions.
This dispute stems directly from several recent documents released by the CFTC.
On October 19, the CFTC published an interim final rule that carves eligible traditional gambling products out of the definition of a "swap". Traditional sports betting and casino games are generally regulated under the gambling rules of individual states and Indigenous tribal nations, with operators required to comply with local licensing, tax, and geographic restriction requirements.
A separate document published the same day remains in the proposed rulemaking stage, and seeks to explicitly include event contracts covering sports, politics, and other topics within the swap definition. If these contracts qualify as federally regulated derivatives, platforms can offer trading for them under the federal regulatory framework. The CFTC has long asserted that federal agencies hold exclusive jurisdiction over event contracts listed on their registered markets, a position that a number of states oppose.
The fair access interpretation published on November 5 pushed the dispute further into platforms’ day-to-day operations. The CFTC required designated contract markets to eliminate U.S.-based geographic restrictions that violate fair access requirements within 30 days; for markets unable to comply, they must submit a written explanation of the reasons for non-compliance to the regulator.
But in some jurisdictions, courts have already ordered platforms to restrict user access to trading. As Schiff and his colleagues noted in their letter, a federal court in California ordered Kalshi to implement geographic restrictions around tribal lands involved in ongoing litigation. The lawmakers argued the CFTC’s new interpretation could conflict with court orders and state and tribal gambling regulations.
Under the U.S. tradition of separating financial and gambling regulatory authority, sports betting and casino games have long fallen under the purview of individual states and Indigenous tribes. Platforms are not only required to apply for licenses and pay local taxes on a state-by-state basis, but also to adhere to geographic restrictions and compliance thresholds set by individual states or tribes.
Once the CFTC frames sports and political event contracts within the legal wrapper of federally regulated derivatives (i.e. swaps), and requires exchanges nationwide to remove domestic geographic fences on the grounds of fair access, long-standing local gambling bans and exclusive tribal gaming domains will face direct disruption at the federal level. In practice, some prediction market platforms have already faced local judicial constraints and regional blocking requirements stemming from disputes over state or Indigenous tribal geographic restrictions. The CFTC’s decision to issue a national unified access interpretation at this juncture effectively acts as an endorsement from federal regulators for platforms looking to bypass local geographic restrictions.
This move quickly spawned a rare cross-party, cross-regional alliance in U.S. politics. On most routine financial regulatory issues, Democrats generally support establishing uniform federal standards, but in this particular standoff, figures including Schiff, Cortez Masto, and Amy Klobuchar, the senior Democratic member of the Senate Agriculture Committee, have chosen to take a firm stance defending state and tribal authority.
On June 8, Klobuchar joined Michael Bennet and other colleagues to call on the CFTC to strengthen retail investor protection and market surveillance. She signed Schiff’s joint letter on November 16, and on November 17 publicly called for respect for state and tribal authority during a nomination hearing for CFTC commissioners. Democratic lawmakers from Nevada and California, joined by Republican Senator Curtis from the conservative state of Utah, have formed a unique united front tied together by the core issue of local gambling regulatory sovereignty.
After the Teleprompter Scandal: How Is the White House Regulating Its Staff?
Beyond this regulatory dispute, prediction markets have raised a new set of challenges: what to do about public officials exploiting their information advantage to place bets on prediction markets?
Under existing statutory text, there are already clear federal red lines prohibiting public officials from using insider information to trade on prediction markets. Section 4c(a)(3) of the Commodity Exchange Act explicitly bars relevant federal personnel from using non-public information obtained through their official duties to engage in specified derivatives trades. On April 30 this year, the Senate also passed Resolution S.Res.708, which directly restricts senators, Senate officers, and employees from trading in events enumerated in the rule. The former targets the act of profiting from insider information itself, while the latter sets participation banlines as part of the Senate’s internal disciplinary framework, with both constraints put in place long before the midterm elections.
Yet a string of high-profile gaps between the letter of the rules and real-world enforcement has continued to roil Washington.
Ahead of the midterm elections, Democratic Senators Elizabeth Warren and Jeff Merkley had been closely monitoring this space. On March 30, the pair joined other colleagues in sending a letter to the CFTC and the Office of Government Ethics, calling on the executive branch to remind federal employees of existing legal obligations and provide compliance briefings. In August, the CFTC reached an enforcement settlement in the high-profile White House teleprompter case.
By October 28, Warren partnered with Republican Senator Curtis to send inquiries to Kalshi and Polymarket, requiring the two platforms to disclose their monitoring mechanisms for election-related contracts. Following the elections, Warren and Merkley sent another letter to the White House Counsel on November 9. This time, they demanded the White House explain whether it had adjusted staff behavioral constraints or implemented internal measures in the wake of the teleprompter case, with a response deadline of November 23.
Faced with mounting pressure, the CFTC moved to issue an enforcement order against Kalshi.
On November 13, the CFTC issued a suspension order against Kalshi, halting trading on specific speech-related contracts on the Kalshi platform, and requiring Kalshi to submit a written response by December 11. The order cited a staff advisory issued on September 22. The advisory reminded trading platforms that when contract settlement depends on whether a person says a specific word, is present at an event, or interacts with a particular individual, a small group of people can influence outcomes. CFTC staff noted that when platforms apply to list such contracts, they should provide more detailed disclosures about how they will prevent market manipulation.
The CFTC noted that after the advisory was published, Kalshi had reused its existing compliance certifications to list the relevant nickname-related contracts. The regulator is currently reviewing these certifications, and has not yet made a final determination on whether the contracts are compliant.
Proponents of prediction markets have long argued that financial incentives can aggregate fragmented information spread across society, generating more accurate predictive signals than traditional opinion polls, and providing hedging tools for market participants. But when the underlying contract is tied to whether a president or public figure will utter a specific word or nickname during a speech, the market has neither genuine commercial hedging demand from real-world businesses, nor widespread public information distributed among the general public to aggregate. Contract outcomes are heavily concentrated in the hands of the speaker, or a small number of aides with advance access to speech drafts. The price discovery mechanism in this scenario objectively devolves into an arbitrage channel enabled by asymmetric insider information.
More tellingly, even the incumbent CFTC, which has taken a proactive stance on sports and event contracts, was forced to hit the pause button on these speech-related contracts on November 13. This move effectively formalized, in official regulatory documents, the manipulation risks inherent to this category of contracts.
Combatting Insider Trading, or Simply Restricting Contract Types Entirely?
After the White House teleprompter case came to light, one of the most straightforward proposed solutions is to restrict public officials from trading on these markets. The Senate has already set internal rules for itself: the April-passed resolution restricts senators, Senate officers, and employees from trading event contracts within the scope of the rule.
However, White House staff, executive branch officials, and other federal personnel still have access to non-public information through the course of their work. Bill S.4188, introduced in March this year, seeks to ban covered federal public officials from profiting from prediction market trades using material non-public information obtained through their official duties. Under this proposed legislation, restrictions target specifically the act of profiting from insider information.
A recommendation released by staff of the House Oversight Committee on November 13 goes even further. The memo, published by the Republican-led committee, suggests considering a ban on a broader set of federal public officials participating in prediction markets, or at minimum restricting them from trading contracts tied to government affairs. Under this framework, regulators would not need to prove a specific trade used insider information to impose restrictions based on the official’s role and the type of contract traded. For now, however, this memo remains at the advisory proposal stage.
Other lawmakers are pushing to directly restrict the types of products platforms can list. Bill S.4226, sponsored by Merkley and co-signed by Warren and other colleagues, would place contracts tied to elections, sports events, military operations, and certain U.S. government actions within the proposed ban scope, with exceptions carved out for government-action contracts used to hedge commercial risk. If this proposal passes, federally registered platforms will no longer be able to offer these product categories to retail traders.
The S.4160 bill introduced by Schiff and his colleagues has a narrower scope, targeting only contracts tied to sports events and casino-style games. Compared to S.4226, it does not include elections and military operations within its ban scope.
There are also lawmakers who want to retain event contracts while tightening trading rules. Bill S.4469, introduced in April by Democratic Senator Kirsten Gillibrand and Republican Senator David McCormick, seeks to revise CFTC’s regulatory rules for event contracts, add retail investor protection requirements, and restrict members of Congress and certain executive branch officials from participating in trades.
All of these bills propose restrictions, but take different approaches. Some first define which events cannot be traded; others allow markets to continue operating, and instead restrict which groups of people can participate. Both S.4160 and S.4469 are introduced by cross-party groups of lawmakers, but they remain proposals at this stage, and will need to go through full congressional review to move forward.
What Awaits Prediction Markets as the Democrats Take Control of Congress?
On January 3 next year, Democrats will take control of both the House and Senate. For prediction market platforms, this means Congress is likely to hold more hearings and launch more inquiries focused on insider trading, contract product categories, and local regulatory authority.
However, winning a congressional majority does not mean the previously proposed restrictions will automatically become law. Bills including S.4226 and S.4160 will still need to go through full congressional review to advance; even if both chambers pass the legislation, the bill will be sent to the president for signature. If the White House exercises its veto power, Congress would need to secure a two-thirds majority in both the House and Senate to override the veto.
CFTC commissioner nominees must also be confirmed by the Senate. During the nomination hearing held by the current Senate Agriculture Committee on November 17, Klobuchar already raised questions with nominees about retail investor protection, state and tribal authority, and other key issues. Whether the new Congress will be able to push through stricter rules depends on whether specific bills can garner sufficient support, and how the White House and CFTC will respond.
In the meantime, Kalshi, which already has a set of speech-related contracts suspended, must submit its written response to the CFTC by December 11. The regulator will then decide how to proceed with its review of these contracts.